Policy Insight

- Details
- Policy Insight
By Ayobami Ayorinde and Seyi Akinbodewa | For the first time in decades, Nigeria’s Federal Government has undertaken a comprehensive tax reform. The journey started with the announcement and inauguration of the Presidential Committee on Fiscal Policy and Tax Reforms, led by Mr. Taiwo Oyedele, a renowned tax expert.

- Details
- Policy Insight
By Adebayo Ahmed | The current cash crunch is the dominant issue in Nigeria today. To go about their daily lives, many people all over the country are spending countless hours on never-ending queues trying to get some money, which they presumably own. With frustration building, as a result of the cash crunch as well as other issues such as the fuel crisis, the obvious question is: “what is the way forward”? Should Nigeria continue as is, hoping that people manage the suffering for real or perceived future benefits? Or do we need a course correction before the lid gets blown off completely and we find ourselves with a severe economic contraction or worse?
The currency change policy
The cash crunch can be linked directly to the policy effort of the Central Bank of Nigeria(CBN). In October 2022, the CBN announced plans to change the currency, replacing the soon-to-be-decommissioned N200, N500, and N1000 notes with new versions. Reasons given for the change ranged from fighting counterfeiting, kidnapping, corruption, money laundering and other forms of illicit financial flows. Additionally, the policy has been touted by some advocates outside of the apex bank as a tool for stopping or limiting vote buying in the upcoming elections. Although there were indirect suggestions that efforts would be made to promote digital transactions over cash going forward, there was no new and explicit statement on cash restrictions beyond what was already in place via the cashless policy when the currency change was announced last October.
Most of the reasons given for the new policy are valid. As pointed out by the CBN, the currency notes being changed had not been redesigned in over 20 years. Improving transparency through increased digital transactions has also been a longer-term goal of the CBN, and a good one too. However, some of the reasons given were on suspicious economic grounds, such as too much cash being outside the banking system. It can be safely assumed that the point of cash is for it to be in circulation and not sitting in bank vaults and that reducing money supply in general would be part of its regular monetary policy operations. Regardless, a currency change was not expected to lead to a significant cash crisis.
However, as has become clear, the actual policy being implemented was not simply a change of the currency but a sort of “demonetisation” process. The expectation of the CBN was that cash being deposited would not be withdrawn one-for-one, but that customers would adopt other non-cash systems. This cash crisis has however exposed some of the weaknesses in the policy approach.
The policy challenge and why
The first key weakness exposed is that the CBN appears to have grossly underestimated the economy’s actual cash needs. By the economy here we mean just regular people who need cash for their livelihoods on a daily basis. As most economists are aware, Nigeria is a sort of dual economy with a significant informal sector. This is important because informality and cash use tend to go hand-in-hand. How large is the informal sector? A report by the National Bureau of Statistics (NBS) estimated that informal activities accounted for 41.43% of all activities, or of GDP, in 2015 (https://www.nigerianstat.gov.ng/download/403). The World Bank similarly suggested that up to 80.4% of employment in Nigeria in 2021 was in the informal sector (https://www.worldbank.org/en/research/publication/informal-economy). The summary is that informality in Nigeria is a norm and hence the financial needs of the informal sector, notably cash, would be just as significant.
Surveys on use of cash in the day-to-day lives of ordinary Nigerians corroborate those accounts. From the Multiple Indicator Cluster Surveys(MICS) published by the NBS last year, only 35.4% of women and 47.2% of men aged 15 - 49 as at 2021 had bank accounts or any other similar set up in any financial institution. The implication of this is that the non-account-holding population use/need cash to survive on a day-to-day basis. In fact, in states such as Bauchi, Jigawa, and Kebbi, less than 8% of women had bank accounts. The most popular reason given was that they did not have a stable income, and apparently they were using cash daily for survival.
The use of cash is not limited to just the lower income segment though. Another survey in 2021 by Enhancing Financial Innovation in Africa (EFINA) asked a subset of adults if they had used cash for payments in the last year. 100% said they had. Only 24% said they had used digital means for making payments in the preceding year. Similarly, 86% said they had received some income in cash in the preceding year. Only 13% said they had received income by digital means. In summary, almost all available information pointed to cash being ubiquitous in the daily life of Nigerians. The failure by the CBN to foresee this necessary cash demand means that it probably underestimated how much demand there would be for the new currency notes.
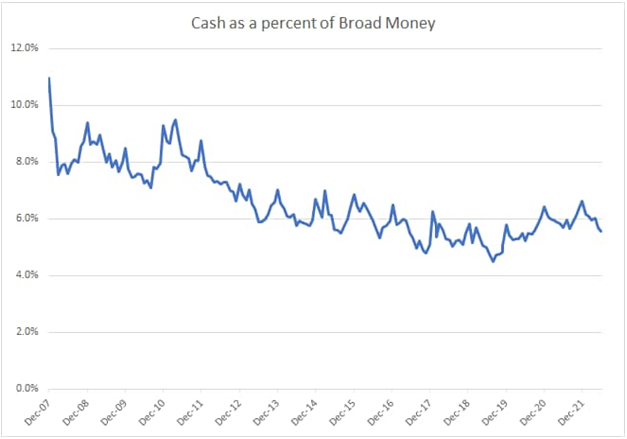
Fig 1: Cash outside depository corporations as a percent of all broad money Source: CBN Quarterly Statistical Bulletin
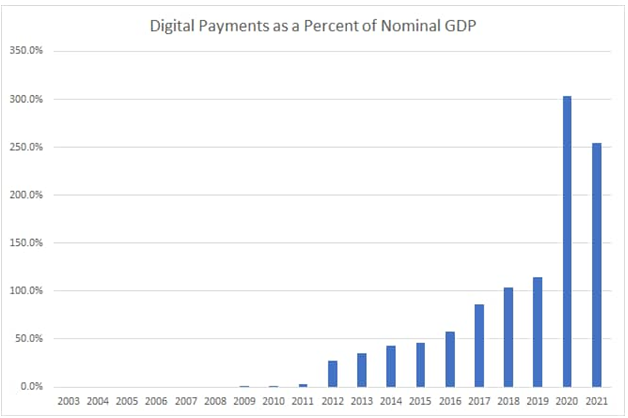
Fig 2: Digital Payments as a Percent of Nominal GDP Source: CBN Quarterly Statistical Bulletin, CBN Statistical Database, Author’s Calculations
The ubiquity of cash does not however mean that Nigeria has not made progress in the move towards a cashless economy. Indeed, due to technological innovations that have put mobile phones in almost every hand and a previously favourable policy environment by the CBN, Nigeria has made tremendous progress in digital finance as evidenced by the continued growth in digital transactions (Fig 2). Nigerian entrepreneurs continue to build innovative products that use the improved digital connectivity to provide financial services to more and more people. On a monetary policy front, cash has slowly become a smaller share of all broad money. As is clear in Fig 1, The percent of cash to all money has fallen from 11% in 2007 to about 5.6% as at June 2022. The percent of cash to GDP has similarly fallen from over 2% of GDP in 2007 to 1.67% as at the end of 2021. For context, a study by the IMF suggested that countries such as the UK, the US, China, and Japan had about 3.5%, 7.5%, 9%, and 20% currency in circulation relative to their GDP (https://www.imf.org/en/Publications/WP/Issues/2019/03/01/Cash-Use-Across-Countries-and-the-Demand-for-Central-Bank-Digital-Currency-46617). By all accounts, Nigeria does not appear to have a cash problem and was already moving in the digital direction even before the currency change. The problem the policy was trying to solve was not really there.
The second key weakness identified is one of unforeseen capacity constraints. On the one hand, and if unofficial information is to be believed, the Nigerian Security Printing and Minting Company Limited - the government owned corporation responsible for printing currency locally - only had the capacity to print about N200billion by the end of January 2023. A long way short of the N2.73 trillion cash in circulation as at September 2022. You do not need to solve too much mathematics here to see why there is a cash crunch. The CBN, via the NSPM PLC, just does not have the capacity to exchange all old notes for new notes even if they wanted to. The attempt by what must have been an enormous number of people looking to quickly migrate to digital platforms also appears to have overwhelmed some of the key financial institutions like NIBSS who must have had very little time to build up capacity. If the Minister of Finance was unaware of the policy in advance, as she told legislators last year, then it is fair to say the banks and associated financial institutions were also unaware.
The consequence of CBN’s failure to properly estimate cash demand, the lack of capacity to actually print new Naira notes, and the unpreparedness of the banks and associated financial institutions to handle the extra demand means that many people in Nigeria are stuck. Long queues at the ATMs that have cash to dispense. Little cash over the counter at the banks. More failures in digital transactions. As with most economic problems in Nigeria, the poor, especially women, are left bearing the short end of the stick. As is clear above, women are much more excluded from the financial systems compared to men. As we also learned during the COVID-19 pandemic, women are much more vulnerable to extra demands on their time due to cultural expectations on activities in the home.
As with other situations involving scarcity of a key commodity, some people exploit the situation for the own benefits. Various examples have been reported in the news already from bank managers looking to give cash selectively to their preferred clients and POS agent looking to make a quick extra buck from desperate customers with few other options. These are all symptoms of the cash scarcity, rather than the cause. We see these practices not only with cash but with FX and fuel. As with other instances, we can spend time and effort sending the secret police and EFCC to harass people but that will be equivalent to taking a pain killer when what you really have is malaria.
Potential outcomes with the status quo
The CBN obviously cannot print enough new currency to meet all the legitimate demand, and the financial system is struggling to cope with the increased demand for its digital services. So, what happens if we retain the status quo with continued cash scarcity? From an economic perspective, that will be tantamount to a sharp reduction in money supply which will most likely be associated with a sharp reduction in economic activity, especially in the informal sector. Sharp reductions in economic activity are typically associated with protests and in some circumstances social unrest. Just as during the COVID-19 pandemic, the how and where these will occur will always be a surprise but they tend to happen. There are some intimations of this already, from banking halls to the streets.
A second consequence of continuing with the status quo is that trust in the banking system will be eroded even more, ironically likely setting back the cashless policy. The banks, and to a large extent the whole financial system, run on trust. Trust that when you put your money in a bank you expect to get it back when you need it. The likely outcome of this cash crisis is that people seek more financial options outside the banking system to limit the risk to their livelihoods in the event something similar happens again.
Policy options going forward
Although some of the objectives of the currency change policy are laudable, the costs to the economy, especially the poor and most vulnerable, are too high to ignore. Very few people can argue against taking actions to tackle kidnappers’ use of cash or to limit the use of cash to influence elections. However, as with every policy, the benefits have to be weighed against the costs. When this cash crisis is combined with the fuel crisis, the already high food inflation, and a competitive election season, then the risk of a self-inflicted recession and social unrest is too high to ignore. It will be tantamount to turning up the heat under a pressure cooker that is already bursting at the seams.
One option will be to increase supply of the new notes by printing abroad. Aside other complications, this will take time and thus will not address the short-term crunch. On the basis of this, the only credible path to reducing the pressure and limiting the economic consequences with the unfortunate effect on the lives and livelihoods of the poorest, is to extend the timeline for the currency change. This should be done with a concerted effort to return some of the old notes into circulation to immediately ease the cash crunch.
If this is done with a new timeline that is far enough that most people do not fear the immediate risk of accepting the old notes, and is communicated clearly and transparently by all parties, then the cash crisis will end. Guaranteed, the reputational damage to the CBN from having to walk back on the policy will be difficult to reverse, but there is no cost-free path now. We can only choose the least costly option. And in doing that, the ego of the central bank should weigh far less than the economic, social and political costs to the entire system.

- Details
- Policy Insight
By Ebehi Iyoha | On 2nd April 2025, a day termed "Liberation Day" by the President Donald Trump administration, the United States announced a slew of unilateral tariff increases on nearly all of its trade partners. In the weeks that followed, some of the new tariffs were paused for 90 days, several products were granted exemptions, and US-China trade relations have significantly worsened through a series of escalating tariffs.

- Details
- Policy Insight
By Wale Thompson | Last week, the Federal Minister of Finance, Budget and National Planning, Mrs Zainab Ahmed announced the receipt of presidential approvals to ‘securitize’ Ways and Means (W&M) loans totaling NGN20trillion which the Federal Government (FG) owes to the Central Bank of Nigeria (CBN). In economics, Ways & Means is the unrestrained central bank financing of fiscal deficits or more simply excessive government borrowing from the central bank to plug financing holes in annual budgets. In her briefing, the minister noted that the securitization would take the form of the issuance of FGN debt instruments of a 40-year tenor and at an interest rate of 9 percent to the CBN in lieu of the amounts owed. Upon completion, the transaction would represent the single largest addition to Nigeria’s federal government debt which would rise to N55.7trillion from the N35.7trillion reported in June 20221.
So, what is this all about?
Securitization is a finance term which refers to the process in which certain assets (usually obligations to receive money e.g. loans) are pooled in a manner that they can be repackaged into interest-bearing securities that can be sold in the capital market. The interest and principal payments from the assets are passed through to the purchasers of the securities.
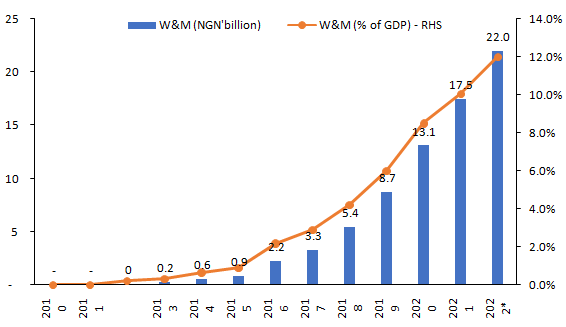
Since 2015, Nigeria’s Federal Government has extensively relied on advances from the CBN to finance fiscal deficits in excess of approved budget amounts. Cumulatively, these advances sum up to N22.1trillion at the end of August 2022 (12 percent of GDP) and were essentially financed by the CBN expanding the monetary base (or simply put: printing money). For context, total FGN domestic debt rose from N8.8trillion in 2015 to N20trillion at the end of June 2022, while the W&M figure went from under NGN1trillion in 2015 to N20trillion in the space of six years, faster than the rate of legislated borrowing plans. Beyond the scale of the increase, the W&M advances present legal problems as these amounts are in breach of provisions within the CBN 2007 Act which not only set a ceiling on W&M borrowings at no more than 5 percent of prior year revenues but also stipulated that new advances cannot be granted without repayment of prior year advances. In addition, the position runs contrary to ECOWAS convergence criteria which sets a 10 percent of prior year revenues as the ceiling for central bank finances to the government within the sub-region.
Figure 1: Cumulative Ways and Means Balances
Source: CBN, NBS
In seeking to convert these W&M advances to FGN debt, the Buhari administration is perhaps signaling a desire to draw the line on the practice as its tenure winds down.
A short history of Ways & Means
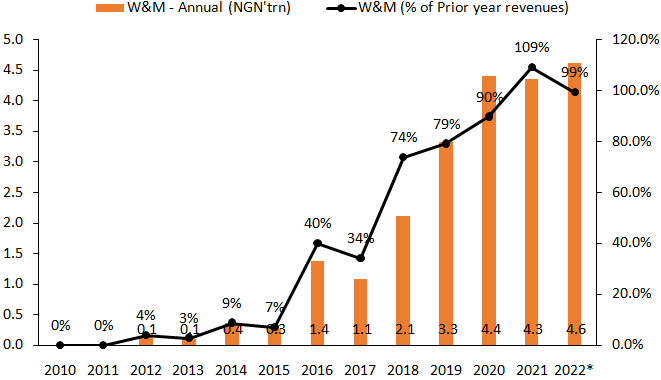
Historically, W&M or to use the proper economics term, unrestrained central bank deficit financing has been observed in two major episodes of Nigeria’s history looking at CBN data going back to independence in 1960. The first episode was during the 1993-2000 era when CBN advances to the FGN in excess of budgeted amounts went from zero to a peak of N34billion in 1996. As a share of fiscal revenues, the amount peaked at 5.4 percent in 1996 and generally stayed within range. In 2007, as part of the CBN 2007 Act, the Obasanjo administration which wound down the Abacha era W&M facilities reduced the limit to 5 percent.
However, the 2015-2022 era is unprecedented in Nigerian history as W&M as a ratio of prior-year revenues hit 109% in 2021. Essentially the CBN generated more money than the FGN in the prior year though 2020 revenues were undoubtedly hurt by the COVID-19 pandemic.
Figure 2: Annual Ways & Means borrowings
Source: CBN, Budget Office.
So, what happened in the last six years?
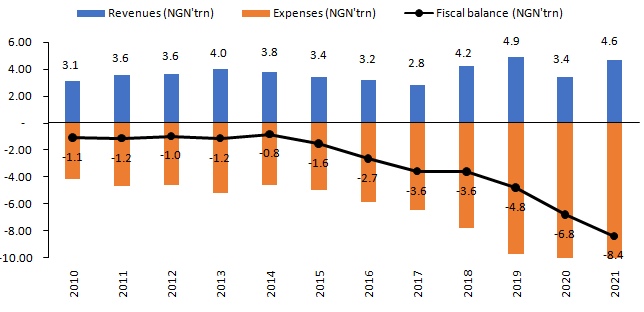
The concurrent collapse in oil prices and Nigeria’s oil production in 2016 cascaded into a drop in FGN receipts. Following the dip in oil prices, Nigeria’s oil exports dropped from an average of USD85billion in 2010-2014 period to USD42billion in 2015 and USD32billion in 2016. In the face of the collapse, the FGN responded by maintaining expenditure levels in a bid to shift the economy out of recession. This bold gamble required financial assistance from the CBN which printed over N1.4trillion in 2016 to sort out the FGN. Rather than being a one-off, the practice soon became embedded as the finance ministry saw a solution to ramping up expenditure levels despite the exit from recession in 2017 and accessible Eurobond financing over the period.
Figure 3: Nigeria Fiscal Accounts.
Source: CBN
When governments run fiscal deficits, they usually borrow to cover the revenue shortfalls to their spending plans. These borrowings have to be approved by the National Assembly as part of the appropriation bill and can be either domestic (via FGN bonds and treasury bills) or foreign via Eurobonds or concessionary loans from bilateral(such as from China, France, India etc.) and multilateral agencies (such as the World Bank, IMF). Once the budget is passed, borrowings have a hard ceiling and when the actual deficit exceeds the projected deficit, the is no legal recourse for the Debt Management Office (DMO) to borrow in excess of the budgeted borrowing amount. To address this, the CBN as the banker to the FG can provide over-draft facilities to meet temporary differences between budget and actual revenues arising from timing differences. For instance, corporate taxes tend to be paid over the third quarter but the government has running costs which need some financing. As such the CBN provides over-draft facilities on these budget accounts. The real problem with W&M is when the actual deficit exceeds the budget deficit by a sizable difference. Given the testy process and haste required in financing these hitherto over-budgeted deficits, the Buhari government found it expedient to simply tap the CBN to extend short-term financing to cover its shortfalls.
So, what is the big deal about Ways & Means?
Unrestrained central bank financing of budget deficits is generally problematic given that it essentially amounts to printing money which raises the money supply. When this exceeds the absorptive capacity of an economy i.e. relative to the amount of goods and services available, economists posit that the excess money supply balances directly fuel inflation. This has its origins in the so-called quantity theory of money by Irving Fisher.
Indeed, over the last six years, the broadest monetary supply aggregate has risen more than double to N49.4trillion (27 percent of, GDP) from N21.6trillion (23 percent of GDP) in 2015. Core inflation, a measure of inflation which excludes food and petrol prices, which tend to be volatile, has averaged 11.8 percent, up from single digit average of 9.5 percent in the preceding eight years. Though not causal, these directional movements suggest links between the expansion in money supply and inflation.
Perhaps one area where the expansion in money supply is likely to pose greater problems is in currency management. Excess money supply balances above an economy’s absorptive capacity are likely to flow outwards towards the purchase of external goods. Given the external account pressures over the last six to seven years, occasioned by the collapse in crude oil prices, the resilience in dollar demand in the face of fairly large currency devaluations hints at an outsized role of the CBN ways and means operation.
What are the implications of this securitization on Nigeria’s economy?
Firstly, Nigeria’s debt metrics are about to change, as the securitization raises debt-GDP ratio to 35 percent of GDP from 23.7 percent at the end of June. While this remains below the recently raised parliamentary ceiling of 40 percent, this development robs Nigeria of the low debt narrative that has appealed to international investors in recent years
Secondly, in terms of debt service costs, the 9% rate (which favourably compares with the current 13.3% weighted average cost of debt on Nigeria’s NGN20.9trillion domestic debt) implies incremental debt service costs of N1.8trillion. For context in the FGN debt service costs in the 2022 budget are set at N3.9trillion. Assuming fiscal revenues continue to tail the N5-6trillion level observed in the last five years, the increase pushes debt-service revenue ratio higher (Jan-July 2022: 84 percent) which presents challenges for future governments.
Thirdly, from a principal repayment perspective, the securitization will potentially add around N500billion in principal repayments (assuming no repayment moratorium and equal amortization) as the FGN is unlikely to fathom having a bullet principal repayment N20trillion in the year 2062. More likely the repayments will be spread over the course of 40years.
From a structural perspective, the action creates some breathing space for the CBN to adopt a more reasonable Naira liquidity management operation. Presently, while printing huge sums of money to plug fiscal deficits, the CBN engages in countercyclical contractionary monetary policy to limit the inflationary blowback of excessive growth in money supply. Unlike in conventional monetary policy when the CBN would sell securities at an interest rate that incentivizes banks to purchase these securities, the CBN engages in a low-cost, mopping-up operation via the use of cash reserve ratio (CRR) debits which costs nothing and more recently the issuance of Special Bills (SPEBs) which are at a yield of 0.5%. Assuming the Buhari government calls time on Ways &Means borrowings, the CBN no longer needs to restrict activity within the banking system as it now has an asset which pays interest and at decent level. Essentially, monetary policy can return to a more conventional path.
How do we prevent another episode of Ways & Means explosion in the future?
Unfinanced fiscal deficits are a function of either poor fiscal budget forecasting, if one assumes that the deviations are naïve mistakes or deliberate fiscal indiscipline. Given the persistently rising pattern of Ways &Means advances under the Buhari administration, one cannot rule out the latter. Combined with the annual ritual of announcing new tax levers to unlock mythical revenue numbers, it is not uncontroversial to say that the finance czars adopted a kamikaze approach to fiscal affairs.
To prevent future abuses, parliamentary oversight must include explicit provisions that prevent the passage of new appropriations bills without explicit borrowing provisions to pay down outstanding unfinanced fiscal deficits. To improve coverage, the finance minister should be made to prepare supplementary appropriation bills in the event of the existence of Ways & Means balances in excess of the statutory 5 per cent limit. Lastly, CBN governors must be made to sign annual declarations that they have not breached Ways & Means. And there should clear and serious consequences, including criminal prosecution and jail sentences, when it is proven that these declarations are false.
*Thompson is an economist with specialization in monetary policy
[1]Source: DMO. Total FGN debt is split across domestic debt (NGN20.9trillion) and external debt (USD40.1billion or NGN14.7trillion).

- Details
- Policy Insight
By Samuel Ajayi and Maryam Ibrahim | In the last 12 months, there have been some significant shifts in the size and structure of the revenues shared to the three tiers of government and other statutory recipients by the Federation Accounts Allocation Committee (FAAC).

- Details
- Policy Insight
By Adebayo Ahmed | Since President Donald Trump was declared the winner of the 2024 election in the US, most of the world started holding its breath, with the level of economic uncertainty inching up multiple notches.
Agora Policy is a Nigerian think tank and non-profit committed to finding practical solutions to urgent national challenges.